We help executives, business owners and family enterprises navigate equity compensation, liquidity events, succession and multigenerational estate planning. AI-powered analysis brings your full picture into view; experienced guidance, coordinated with your CPA and attorney, shapes the strategy.
A clear process from first conversation to annual review.
STEP 1
Discover
We learn your goals, your business and your family's priorities.
STEP 2
Analyze
We model valuation, cash flow, coverage gaps and retirement readiness.
STEP 3
Design
We present options side by side, with the trade-offs in plain numbers.
STEP 4
Implement
We coordinate with your attorney and CPA to put the plan in place.
STEP 5
Review
We revisit the plan each year and whenever your business changes.
Financial tools
Run the numbers before we meet
Use our retirement and life insurance calculators, or request an AI-powered estate plan outline or business insights report to bring to your first conversation.
A trusted partner for the decisions that matter most
Plan with Clarity. Live with Confidence.
Nova Wealth Partners is a trusted partner that pairs AI-powered insight with personal, long-term guidance, helping executives and families plan, protect, grow and pass on wealth.
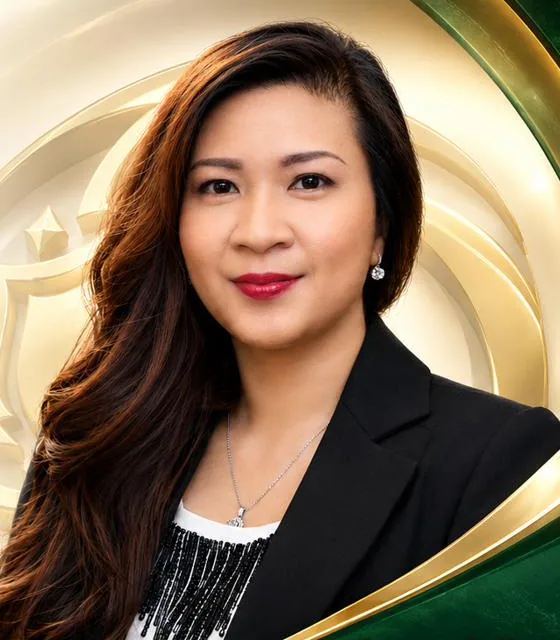
Founder, CEO
Thu Tracy Nguyen
Build with purpose. Protect with strategy. Create a lasting legacy.
Financial success can happen quickly. Building lasting financial security takes intention.
With nearly a decade in financial services and insurance, Tracy works with executives, entrepreneurs, business owners and families whose financial lives have grown complex. For tech executives and founders, wealth often reaches well beyond salary: RSUs, stock options, concentrated equity, real estate and liquidity events bring opportunity, and complexity with it. Her approach starts with the whole picture, not a product.
Tracy spent more than seven years with New York Life, where she grew from licensed agent to Partner, recruiting, training and mentoring a team of more than 10 financial professionals. She later co-founded and led Digital Kauri, Inc. as CEO. That mix of financial services, leadership, entrepreneurship and technology gives her a natural connection with people who build, innovate and lead.
She founded Nova Wealth Partners in 2026 to pair experienced guidance with AI-enabled technology that organizes financial information, surfaces planning gaps and opportunities, and supports better-informed conversations. Technology enhances the analysis. Human expertise guides the strategy. She works alongside clients' CPAs, attorneys and other advisors when a coordinated strategy is needed.
Based in Santa Clara, California, Tracy works with clients in English and Vietnamese.
Tracy
A welcome from Tracy
Why I started Nova Wealth Partners
A short message from our founder on how we work with executives, families and family enterprises, and what to expect from a first conversation.
Areas of focus
Wealth protection & risk management
Life insurance strategies
Retirement & long-term financial security
Executive & business planning
Business continuity & succession
Multigenerational wealth & legacy planning
Licenses & education
Licensed Life & Health Insurance Agent, California [License #]
Retirement Income Certified Professional (RICP®) program, The American College of Financial Services
Advisory for every stage of a business and a family
Your Wealth. Our Focus.
We provide analytical and numerical financial information and business advisory in five connected areas. Most clients start with one and find they touch several.
Business protection
Keep the business running and its owners treated fairly if an owner dies, becomes disabled or leaves.
What we cover
Buy-sell agreement funding
Business continuity planning
Owner disability and loss scenarios
Loan and debt protection
What you receive
A risk exposure analysis
Funding options compared side by side
Coordination with your attorney on agreements
How buy-sell funding works
Explainer · 33 sec
Step 1Two owners share one business, 50/50.
Step 2Each owner holds a life insurance policy on the other.
Step 3If Owner B passes away, B's policy pays its death benefit to Owner A.
Step 4Owner A uses it to buy B's share from B's family, at the price set in the agreement.
The resultThe business carries on. The family is paid fairly and quickly.
Simplified cross-purchase illustration. Your attorney drafts the agreement.
Key employee protection
Protect the company from losing the people who drive its revenue, and give them reasons to stay.
What we cover
Key person life and disability coverage
Executive bonus plans
Deferred compensation strategies
Retention and "golden handcuff" design
What you receive
An estimate of each key person's financial impact
Coverage and retention options with costs
Succession & exit planning
Decide who takes over, when and on what terms, whether that's family, partners, employees or an outside buyer.
What we cover
Exit timeline and readiness
Family, partner and management transitions
Third-party sale preparation
Post-exit income planning
What you receive
A written succession roadmap
Retirement income projections after the exit
Business valuation
Know what your company is worth. That number drives your buy-sell agreement, coverage amounts and exit strategy.
What we cover
Earnings and revenue-based valuation methods
Industry benchmarks
Value drivers and detractors
What you receive
An indicative valuation range
Actions that could raise the value before a sale
Legacy planning
Pass wealth to the next generation and the causes you care about with clarity, liquidity and fewer surprises.
We recommend products only after the analysis is done. Here is an overview of what we work with and what each one is typically used for.
Life insurance
Used for income replacement, business protection, estate liquidity and wealth transfer.
Temporary coverage
Term life insurance
What it is
Coverage for a set period, such as 10, 20 or 30 years, typically at the lowest initial cost.
Often used for
Income replacement, mortgages, buy-sell funding and key person coverage.
Keep in mind
Coverage ends when the term ends unless it is converted or renewed.
Permanent · flexible
Indexed universal life (IUL)
What it is
Permanent coverage with cash value that can earn interest linked to a market index, subject to caps and floors.
Often used for
Lifetime protection, supplemental retirement income and executive benefit plans.
Keep in mind
Needs regular review. Costs, caps and participation rates can change.
Permanent · guaranteed
Whole life insurance
What it is
Lifetime coverage with fixed premiums and cash value that builds on a schedule set by the insurer. Some policies may also pay dividends, which are not guaranteed.
Often used for
Estate planning, legacy goals and conservative long-term savings.
Keep in mind
Higher premiums than term for the same death benefit.
Term, whole and IUL at a glance
Explainer · 19 sec
1 · How long coverage lastsTerm covers a set period. Whole and IUL are built to last a lifetime.
2 · How cash value builds (concept)Term has none. Whole life builds steadily. IUL credits interest tied to an index, with a floor.
Concept only, not a projection. Flat steps show years the index floor applies.
3 · How premiums workEach policy fits a different goal. We compare them side by side for you.
Client education
The Rockefeller Legacy
How life insurance helped some of America's best-known families preserve and pass on their wealth, and the lessons any family can apply.
Annuities
Used to protect principal and create predictable income in retirement.
Growth + protection
Indexed annuities
What it is
A contract that credits interest based on a market index while protecting principal from market losses.
Often used for
Principal protection, tax-deferred growth and guaranteed lifetime income options.
Keep in mind
Surrender charges may apply during the early years. Gains are limited by caps or participation rates.
Retirement plans
Tax-advantaged accounts for owners, employees and individuals.
Employer plan
401(k)
Best for
Businesses offering a retirement benefit, with optional employer matching.
Highlights
Pre-tax or Roth contributions and higher contribution limits than IRAs.
Employer plan
403(b)
Best for
Employees of nonprofits, schools, hospitals and certain public organizations.
Highlights
Works much like a 401(k), with possible catch-up provisions.
Individual
IRA (Traditional & Roth)
Best for
Individuals saving on their own or rolling over an old employer plan.
Highlights
Tax-deferred or tax-free growth, depending on the type.
Small business
SEP IRA
Best for
Self-employed people and small businesses that want a simple plan.
Highlights
Employer-funded, with flexible contributions each year and low administration.
Owner-only
Solo 401(k)
Best for
Business owners with no employees other than a spouse.
Highlights
Contribute as both employee and employer for high savings potential.
Product guarantees are backed by the financial strength and claims-paying ability of the issuing insurance company. Indexed products do not directly participate in any stock or equity investments. Contribution limits and eligibility rules for retirement plans are set by the IRS and change periodically. [Add compliance-approved product disclosures.]
Financial tools
Run the numbers
AI-powered insight. Personal guidance.
Educational calculators and AI-assisted reports to help you prepare for a conversation with your advisor. Results are estimates, not advice.
Projected balance–
In today's dollars–
Est. monthly income*–
*Estimated monthly income uses a 4% annual withdrawal rule of thumb, in today's dollars. Projections assume a constant return and are hypothetical. They do not represent any specific investment or product, and actual results will vary.
Total need–
Resources in place–
Estimated coverage gap–
This is a simplified estimate for educational purposes. Your actual needs depend on taxes, other income sources, business obligations and personal goals. Talk with a licensed professional before buying coverage.
Your estate planning roadmap will be sent to you.Answer the questions, add your contact details and select Request an access. We review every request and email your personalized roadmap, usually within one business day.
AI-generated for educational purposes only. It is not legal, tax or investment advice. Estate planning documents should be prepared by a licensed attorney.
Your business insights report will be sent to you.Answer the questions, add your contact details and select Request a report. We review every request and email your report, usually within one business day.
AI-generated for educational purposes only. Valuation figures are illustrative ranges, not a formal appraisal. This is not legal, tax or investment advice.
Contact
Schedule a conversation
Book a complimentary conversation directly, or send a message and we'll reply within one business day.
Schedule directly
Pick a time that works for you for a 30-minute introductory call.